The Bag File: Insuring a Michael Kors Outlet Find Without the Paperwork Panic
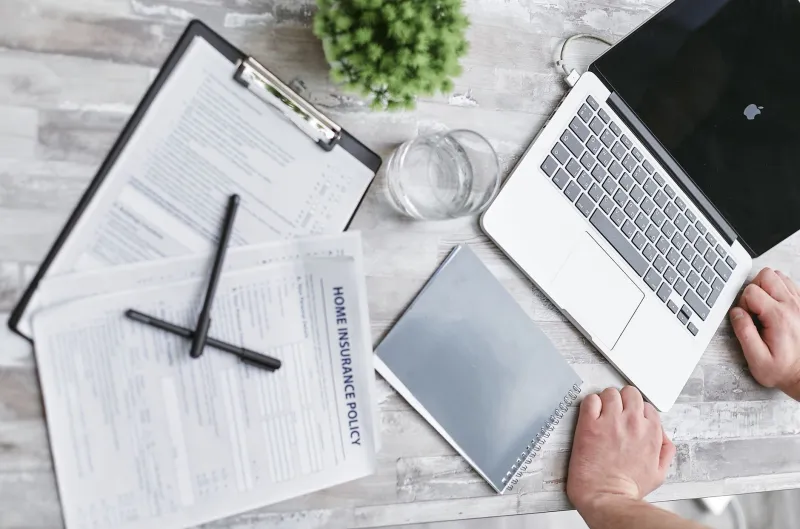
There is a particular kind of optimism in the way we treat receipts. We fold them into the inner pocket, tell ourselves we will file them later, and then the bag goes into rotation and the receipt goes soft at the edges. By the time anything goes wrong, the proof of purchase is a pale slip behind the cutlery drawer, and the bag is just a bag again — except it is not, because it cost real money and you would like the insurance to agree.
The receipt in the inner pocket is not a filing system
Most of us insure our homes and then quietly hope the subject never comes up. A handbag sits somewhere between an everyday item and a small asset. In a UK home contents policy, that middle ground is where the paperwork gets interesting.
What UK contents policies tend to do with handbags
Contents insurance usually covers theft and damage to belongings inside the home. Cover for items taken outside — on a train, in a café, in the boot of a car — is often an optional add-on, sometimes called personal possessions cover. Handbags can also fall under a valuables limit, which is a sub-limit inside the main policy. The exact wording varies by insurer, so the useful move is to read the policy schedule rather than the glossy summary.
Two phrases are worth knowing. The single article limit is the maximum the insurer will pay for any one item without it being listed separately. It might be £1,000, £1,500 or £2,000; it depends on the policy. New for old means a replacement of similar quality rather than a payout based on wear and tear. If your bag cost more than the single article limit, or you want it covered away from home, you may need to specify it.
The moment a bag becomes a specified item
A bag does not need to be a collector's piece to be worth naming on a policy. If the outlet price is close to or above the single article limit, or if you have several bags that together push you over a total valuables cap, it is worth a phone call. Specifying an item usually means listing it on the schedule with a description and a value. Some insurers ask for a valuation or a receipt; others simply want the details. The point is to have the conversation before you need to claim, not after.
What an insurer actually asks for
When a claim happens, the questions tend to be practical: what was it, where did it come from, what did you pay, and can you prove it? For a theft, you may need a crime reference number. For a loss, you may need a statement of what happened. For damage, photographs help. In every version, proof of ownership and proof of value are the two pillars.
That is why the outlet receipt matters. It shows the date, the shop, the amount paid and often the style details. A bank statement alone can show a payment but not what it bought. A photograph of the bag is useful, but a photograph of the bag with its receipt and tag is better.
The ten-minute bag file
This is the whole routine. Do it on the day you buy, while the bag is still exciting and the receipt is still crisp.
- Photograph the receipt. Lay it flat in good light. Capture the whole slip, including the shop name, date, total and any style code. Thermal receipts fade; a photo is your backup.
- Photograph the tag. The swing tag usually carries the model name, colour and sometimes a style number. This is the language an insurer or a repairer will understand.
- Take four bag photos. Front, back, interior label and a close-up of the hardware or zip. Do it on a plain surface. No need for styling.
- Note the date and price. A short note in your phone is enough: bought 13 November 2026, Michael Kors outlet, model and colour, price paid.
- Make a folder. Call it something obvious, like MK bag file, and keep it in cloud storage. A folder you can find in a hurry is worth more than a perfect system you never open.
- Add it to your home inventory. If you already have a list of valuables for insurance, add the bag. If you do not, this is a reasonable moment to start one.
- Check the limit. If the price is above your single article limit, ring your insurer and ask about specifying it. Ask about away-from-home cover at the same time.
Why the outlet receipt deserves its own photo
Outlet purchases can come with slightly different paperwork. The receipt may be a standard till slip rather than a gift receipt, and the packaging may be simpler. That does not make it less valid; it just makes it more important to capture the details before they fade. If you are buying as a gift, ask for a gift receipt and photograph both. If the bag is a present to yourself, treat the receipt like part of the bag for the first ten minutes.
The shoebox-of-doom test
The shoebox of doom is the place where receipts go to become confetti. You know the one. It lives on top of a wardrobe and contains a takeaway menu, a passport photo and a receipt for something you returned years ago. If your bag proof would end up there, it is not really proof. The bag file is the opposite: one folder, one habit, ten minutes.
A small habit, not a big worry
None of this is about expecting the worst. It is about making the boring part easy, so that a lost bag is an inconvenience rather than a saga. If you do nothing else this week, photograph the receipt and the tag of your newest Michael Kors outlet bag. Then put the original somewhere you can find it. The bag can go back in the wardrobe; the file can do the quiet work.